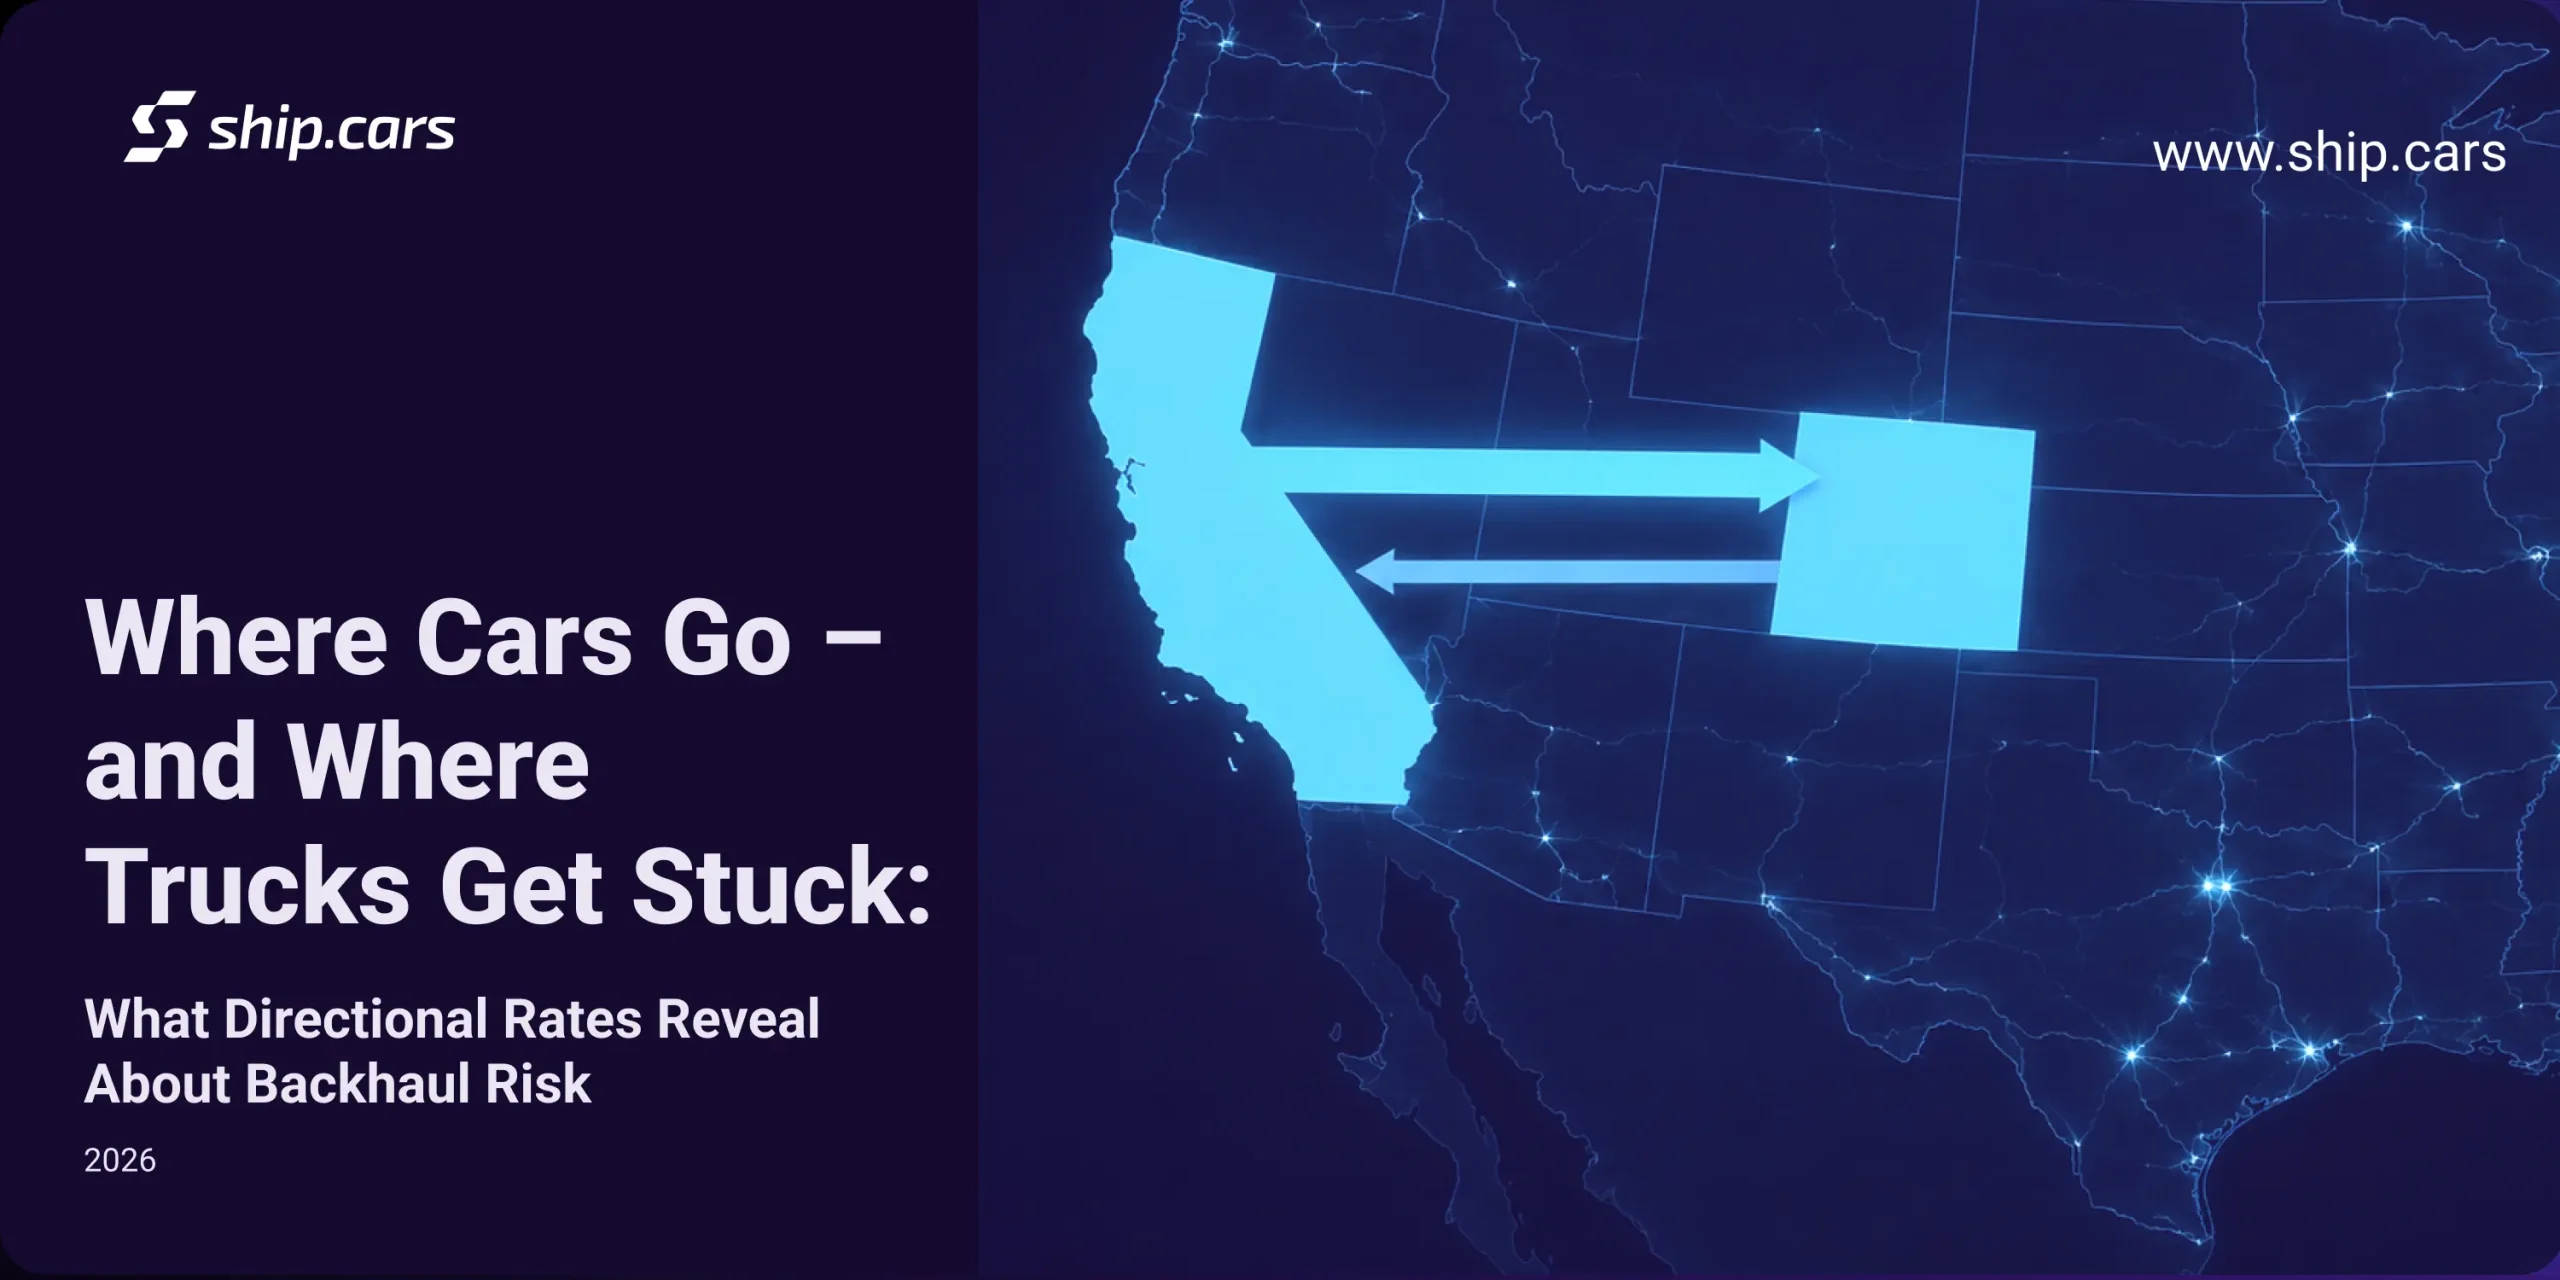
Directional auto transport rates can vary materially depending on which way the truck is moving, even across the same state pair and similar trip distances. Using pricing data from August 2024 through August 2026, we analyzed where those directional differences are strongest, how they compare with inbound and outbound movement, and what they can mean for carriers planning the next leg of a trip.
Below, you’ll see which states show the strongest backhaul pressure and which lean toward stronger outbound pricing, along with the key questions carriers should ask when a load looks especially attractive on the first leg.
Why do directional auto transport rates matter when picking loads?
The difference becomes clear when we compare the same state pairs in opposite directions.
Our analysis compares median price per mile per vehicle between the same states and within similar distance ranges. That keeps shorter moves from being compared directly with much longer ones simply because they happen to enter or leave the same state.
Here are three examples from the dataset:
| Corridor / distance | Direction | Median $/mile/load | Directional Difference |
|---|---|---|---|
| California ↔ Colorado, 700–1,400 mi | CA → CO | $0.73 | ~49% higher than CO → CA |
| CO → CA | $0.49 | – | |
| California ↔ Texas, 1,400+ mi | CA → TX | $0.55 | ~38% higher than TX → CA |
| TX → CA | $0.40 | – | |
| Texas ↔ Arizona, 700–1,400 mi | TX → AZ | $0.51 | – |
| AZ → TX | $0.67 | ~31% higher than TX → AZ |
For a dispatcher, those differences are more than market statistics. A California-to-Colorado move at a median $0.73 per mile creates a different follow-up position than the same corridor in reverse at $0.49 per mile.
The same applies between California and Texas. A load going into Texas may look attractive on its own, but if the opposite direction has historically paid less, that changes the economics of the wider trip.
Where does the directional difference show up most?
Looking across states is what makes those patterns easier to see.
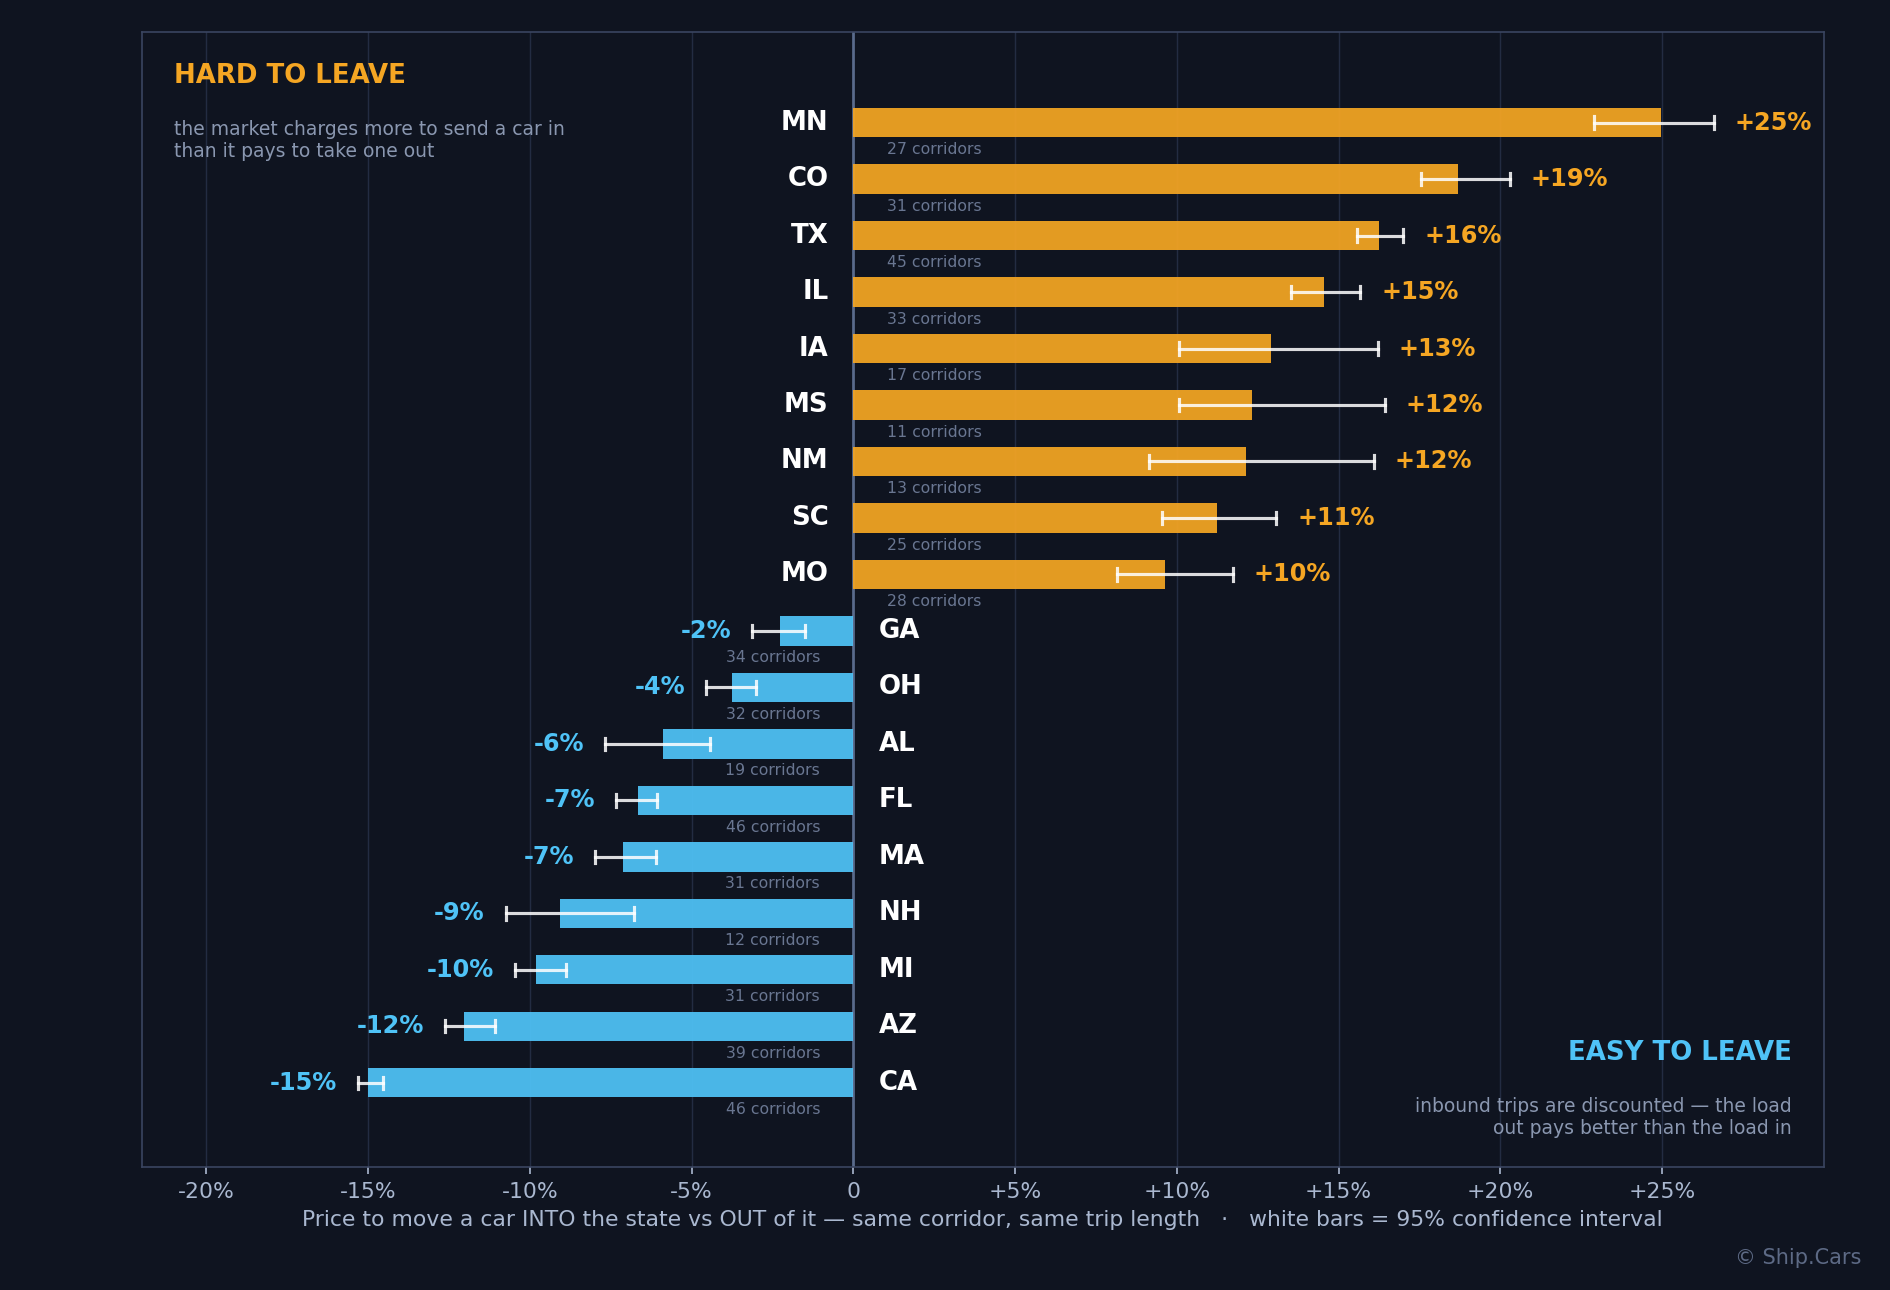
Minnesota sits at the strongest positive end of the featured chart at +25%, followed by Colorado at +19% and Texas at +16%. On the other side, California shows −15%, while Arizona sits at −12%.
That does not make Minnesota a “bad” state or California a “good” one. The index is not measuring how long a truck will sit, whether a backhaul will definitely be available, or how far a carrier will need to deadhead.
It is showing a pricing relationship.
If a dispatcher sees a particularly strong load into Minnesota, the practical question is whether that rate still works for the operation if comparable outbound pricing has historically been weaker.
California presents the opposite pattern. A load going into the state may not always look as attractive in isolation, but stronger historical outbound pricing could improve the economics of what follows, depending on the actual lane, timing, truck position, and available freight.
A weaker immediate return does not automatically make the first load a poor choice either. Some carriers have enough flexibility to wait, build a fuller return trip, or route through a third market instead of forcing a direct round trip. In those cases, the value of the destination depends partly on how much flexibility the operation has to build the next move.
More outbound movements do not always mean better outbound rates
The logical thing would be to think that if more vehicles are moving out of a state, the outbound direction should also pay better.
But when we compare movement share with directional pricing, it is not that simple.
Colorado is a good example. Among qualifying movements in our dataset, 52.3% were outbound and 47.7% inbound, yet the state still showed a +19% directional rate index. Slightly more vehicles were moving out, but the outbound direction was still priced lower.
Illinois shows a similar pattern. 53.1% of qualifying movements were outbound, compared with 46.9% inbound, yet the state had a +15% directional index.
California goes the other way. Its movement split was relatively balanced at 51.2% outbound and 48.8% inbound, but the directional index was −15%, meaning outbound pricing was materially stronger.
For a dispatcher, there is an important distinction here: “there are loads going out” is not the same as “the loads going out pay well”.
A busy load board can still produce a weak recovery move. If the available loads do not fit the truck on rate, distance, timing, capacity, or route, the number of postings matters much less.
What does this change when you are picking loads?
This is where directional-rate data becomes useful in day-to-day dispatching. Imagine a dispatcher comparing two loads for the same truck. The first pays very well but delivers into a market where outbound pricing has historically been weaker. The second pays slightly less but leaves the truck somewhere that may be easier to build around.
The higher-paying load may still be the right choice. Driver hours, available capacity, pickup timing, fuel, customer commitments, and the actual opportunities available at that moment can all outweigh a historical directional pattern.
The options also look different depending on the carrier.
An established carrier may already have direct relationships with dealers, brokers, auctions, or other shippers in the destination market. Some of the next loads may reach that carrier directly before they ever appear on a public load board. A newer carrier, however, may be much more dependent on what is publicly available. In that situation, getting into a market at a strong rate is easy. Finding a workable way out is what determines whether the wider trip still makes sense.
The recovery move does not have to be a direct backhaul either. A carrier running California → Colorado may decide that Colorado → California is not the best move and instead build something closer to California → Colorado → Texas → California. Another operation may have the flexibility to stay in a market briefly while dispatch builds a better return rather than taking the first available load simply to get the truck moving.
The best strategy really depends on the carrier’s network, customers, equipment, driver schedule, and tolerance for waiting. Directional pricing is useful because it gives the dispatcher another signal about where additional planning may be worthwhile.
This is also where revenue per loaded mile and revenue per total mile can tell different stories. Revenue per loaded mile only reflects the miles where the truck is carrying freight. Revenue per total mile also accounts for the miles the truck travels empty, which can change the picture if a strong first leg is followed by significant deadhead or a weaker recovery move. A slightly lower-paying first load may work better overall if it helps keep the truck loaded for more of the route.
Before committing to the trip, check:
- What has the likely recovery direction historically paid?
- If preferred loads are not available, how much deadhead or waiting could the alternative create?
- Could another market or an additional vehicle improve the second or third leg?
- How do driver hours, available capacity, and stop order affect the route?
- Does the trip still work when you look at revenue per total mile, not only revenue per loaded mile?
For carriers using the Ship.Cars SmartHaul TMS, Trip Builder can help model that wider picture before every load is committed. Dispatchers can combine booked loads with posted load board opportunities that have not been booked yet, or add a load candidate using basic details such as locations, vehicle, and price. This makes it possible to compare how different second- or third-leg options affect the route without turning every possibility into a booked load.
The feature supports the planning process rather than making the decision for the dispatcher.
Directional pricing is most useful as a planning signal. It can show where entering and leaving the same market have historically produced meaningfully different pricing, and where a load or route may deserve a closer look before the truck is committed.
That signal is not a rule about which states to avoid or which loads to take. Current rates, actual load availability, customer relationships, truck capacity, driver hours, route fit, and timing still matter. But when the market has shown a consistent directional imbalance, that is useful context to bring into the dispatch decision rather than discovering it only after delivery.
Methodology: This analysis covers qualifying auto transport movements from August 2024 through August 2026. It compares median price per mile in both directions within the same state-to-state pairs and similar distance ranges. The analysis includes open transport, running vehicles, single-vehicle moves over 50 miles, with rate and payment filters applied to reduce extreme observations.