Figures below are percentage changes only – Ship.Cars doesn’t disclose absolute volumes or rates. Directional signal, not a forecast. Full methodology at the end.
In short
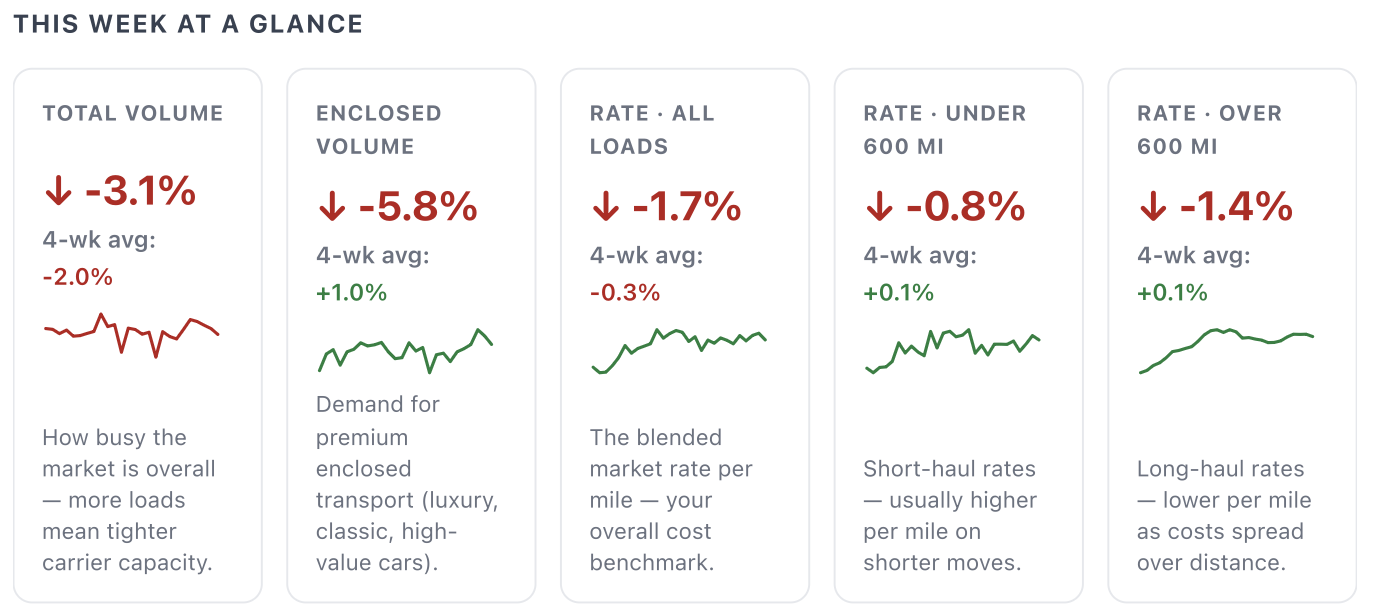
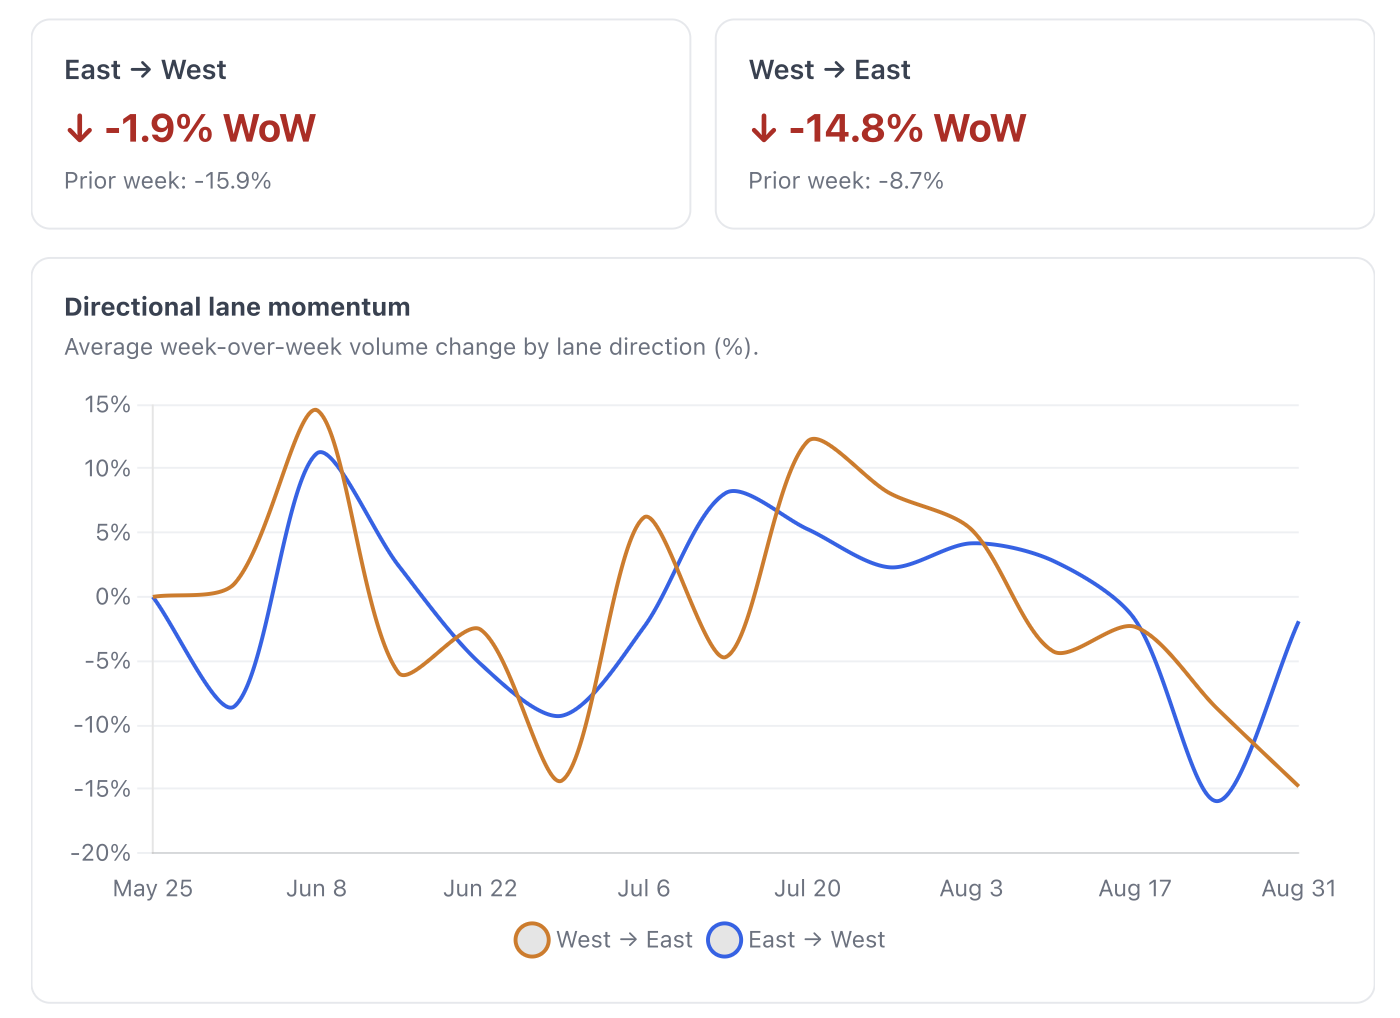
- Demand fell for a fourth straight week, and the decline widened rather than eased (-3.1% after -1.8%), pulling the four-week trend into negative territory for the first time in this stretch. The cross-country story flipped direction. Last week it was East→West falling sharply while West→East held; this week the pattern reversed – East→West steadied at -1.9% while West→East fell -14.8%, its steepest single-week decline in our series. Coast-to-coast freight has now been repriced lower in one direction or the other for two weeks running.
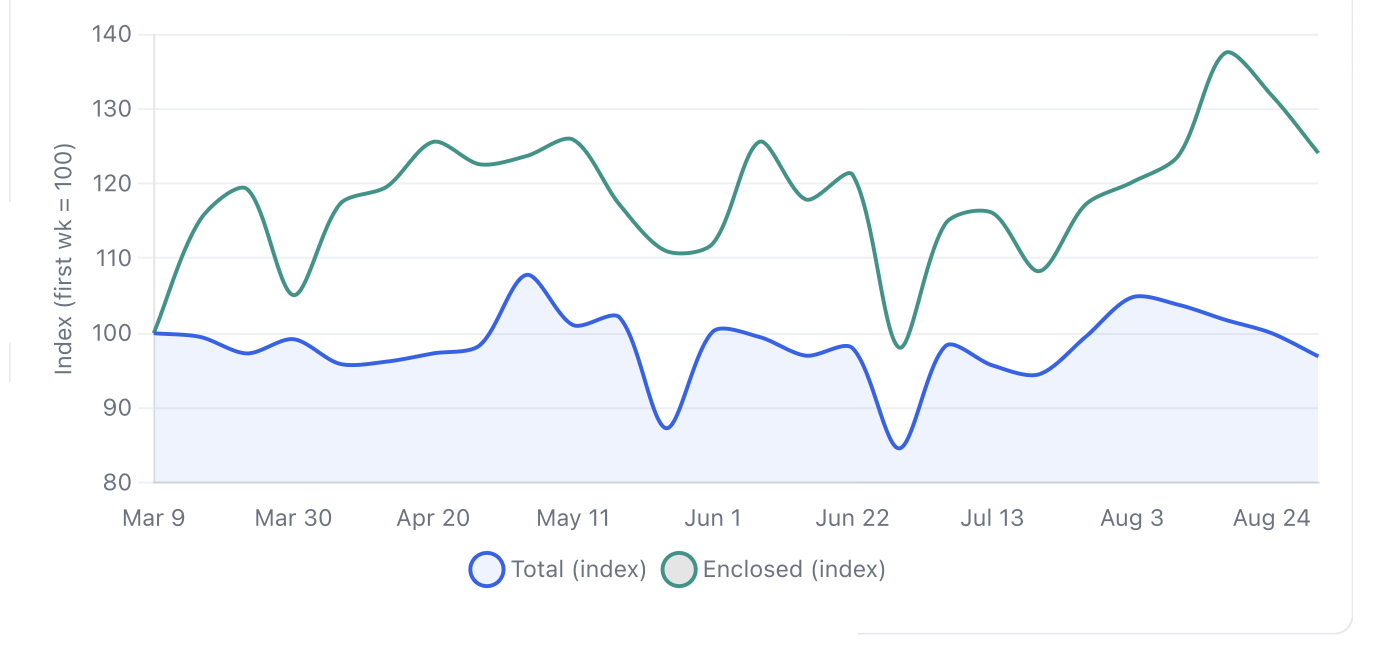
- Auto transport rates gave a little ground for the first time in this slide. Every segment we track eased – blended, short-haul and long-haul rates all softened modestly, and even the small-sample enclosed segment was roughly flat. It’s a mild move on a four-week view, but it is the first week rates moved with volume instead of holding against it. Regional breadth narrowed to just two advancing markets, and one region that had spiked the prior week gave essentially all of it back.
Volume trend
Pricing trend
Price segment detail
| Segment | WoW | 4-week average |
|---|---|---|
| All loads | ↓ -1.7% | ↓ -0.3% |
| Short-haul · under 600 mi | ↓ -0.8% | ↑ +0.1% |
| Long-haul · over 600 mi | ↓ -1.4% | ↑ +0.1% |
| Enclosed (premium) (volatile) | ↓ -0.4% | → -0.0% |
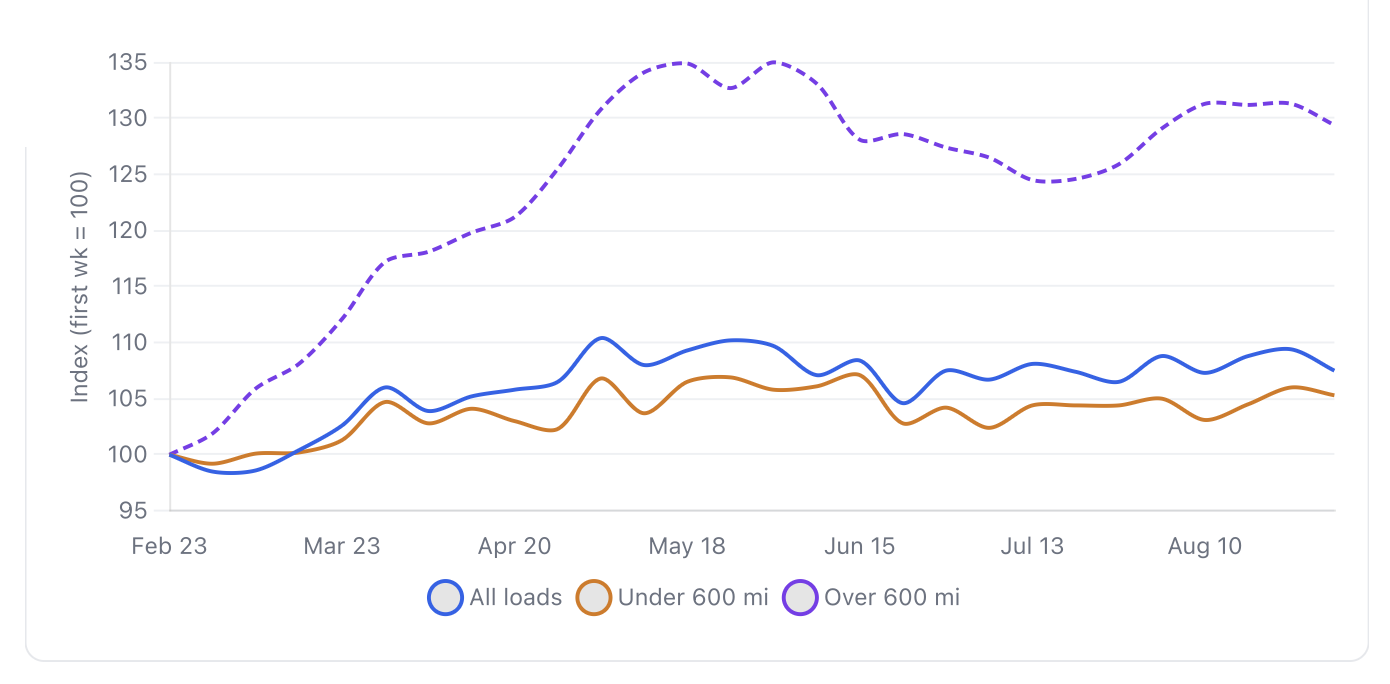
Short-haul rates typically run higher per mile (fixed pickup/delivery effort over fewer miles); long-haul runs lower per mile.
Enclosed (premium) is a small-sample segment, so single weeks can swing for reasons that have nothing to do with the wider market – read it on a multi-week basis rather than week to week. It is excluded from the rate index chart above so that sample noise does not distort the rebased lines.
Lane deep dive
Region deep-dive – volume & rate
Regions: NE – Northeast; SE – Southeast; SW – Southwest; MW – Midwest; NW – Northwest; South – South/South-Central
| Region | Volume WoW | Rate/MI WoW | Volume Trend |
|---|---|---|---|
| MW | ↓ -7.0% | ↓ -1.3% | Weakening |
| SE | ↓ -1.3% | ↓ -0.3% | Improving |
| SW | ↑ +1.4% | ↓ -0.5% | Improving |
| NE | ↓ -6.3% | ↓ -3.2% | Weakening |
| South | ↑ +4.1% | ↑ +0.9% | Improving |
| NW | ↓ -17.9% | ↓ -2.0% | Weakening |
Volume and rate/mile WoW by region. | Breadth narrowed to just two advancing markets: the South rose on both volume and rate – the clearest sign of genuine tightening on the board this week – and the Southwest edged up on volume alone. The other four regions eased, led by the Northwest, which gave back nearly all of its outsized prior-week gain along with a modest rate pullback. The Midwest and Northeast posted the next-largest declines, with the Midwest’s swing the widest single-week reversal among the six. The trend column compares this week’s volume change with last week’s.
What the data is telling us
- Demand fell for a fourth consecutive week (-3.1%, after -1.8%, -2.0% and -1.0%), and unlike the prior three prints, this one widened rather than shrank. The four-week average has now turned negative at -2.0%. A holiday falls at the very start of the next data week, which historically produces an outsized single-week drop that fully reverses the week after – worth keeping in mind when the next print lands.
- The coast-to-coast lanes swapped roles. East→West, which fell sharply last week, steadied at -1.9%, while West→East reversed hard, falling -14.8% – the steepest single-week move for that direction in our series. Two straight weeks of one cross-country direction pulling back hard, while the other direction and regional freight held comparatively steady, suggests carriers are repositioning rather than the whole long-haul market softening at once.
- Auto transport rates eased across every segment for the first time in this four-week volume slide. The blended rate moved -1.7% (-0.3% on four weeks), short-haul under 600 mi eased -0.8%, and long-haul over 600 mi eased -1.4%. It’s a modest move – the four-week averages are still close to flat – but it is the first week rates gave any ground alongside falling volume, worth watching for confirmation next week.
- Premium enclosed volume declined for a second straight week (-5.8%), extending its pullback from the mid-August peak. Its four-week average of +1.0% is still comfortably positive, so this reads as cooling off a strong run rather than a reversal, but a third down week would change that read. The enclosed rate barely moved (-0.4%).
- Regional breadth narrowed to just two advancing markets. The South rose +4.1% with its rate up +0.9% – volume and price moving together, the clearest tightening signal on the board – while the Southwest edged up +1.4% on volume alone. Everything else eased: Southeast -1.3%, Northeast -6.3%, Midwest -7.0% and Northwest -17.9%.
- The Midwest gave back essentially all of last week’s gain, swinging from +4.8% to -7.0% with its rate down -1.3% – the widest single-week reversal of the six regions. Treat last week’s Midwest strength as a one-week pop rather than a new baseline.
- The Northwest’s prior-week spike has now fully unwound: after a very large prior-week gain it fell -17.9% this week, with its rate also down -2.0%. That confirms the spike was a one-off rather than the start of a sustained regional tightening, and the region’s baseline should be read at something closer to its pre-spike level going forward.
What to watch: Four weeks of volume decline, and this is the first one that widened and the first one rates moved with rather than against – together a mild signal that the market is cooling, not just thinning. A holiday falls at the start of the next data week, and holiday weeks in this series routinely print sharp single-week declines that fully reverse the following week, so treat the next headline as a calendar effect rather than a trend confirmation. Beyond it, the questions worth tracking are whether West→East’s sharp pullback reverses the way East→West’s did, whether rates continue easing or snap back as this week’s provisional prints firm up, whether enclosed avoids a third straight decline, and whether the South’s clean volume-and-rate tightening holds through the holiday disruption. For standard open-carrier moves, normal lead times and stable budgeting still apply; for enclosed and high-value vehicles, book earlier.
– Vlad Kadurin, Chief Product & Operations Officer
Methodology: Ship.Cars Market Read reflects marketplace activity for the last complete Monday–Sunday week (August 31 – September 6, 2026). Every figure is a week-over-week or 4-week percentage change — absolute volumes and rates are not disclosed. Rate movements are calculated using a distance-adjusted methodology that compares loads within distance bands and limits the influence of extreme per-mile values. Figures are directional indicators, not a forecast, and may be revised as late loads post. Refreshed weekly. For informational purposes only.