Figures below are percentage changes only – Ship.Cars doesn’t disclose absolute volumes or rates. Directional signal, not a forecast. Full methodology at the end.
In short
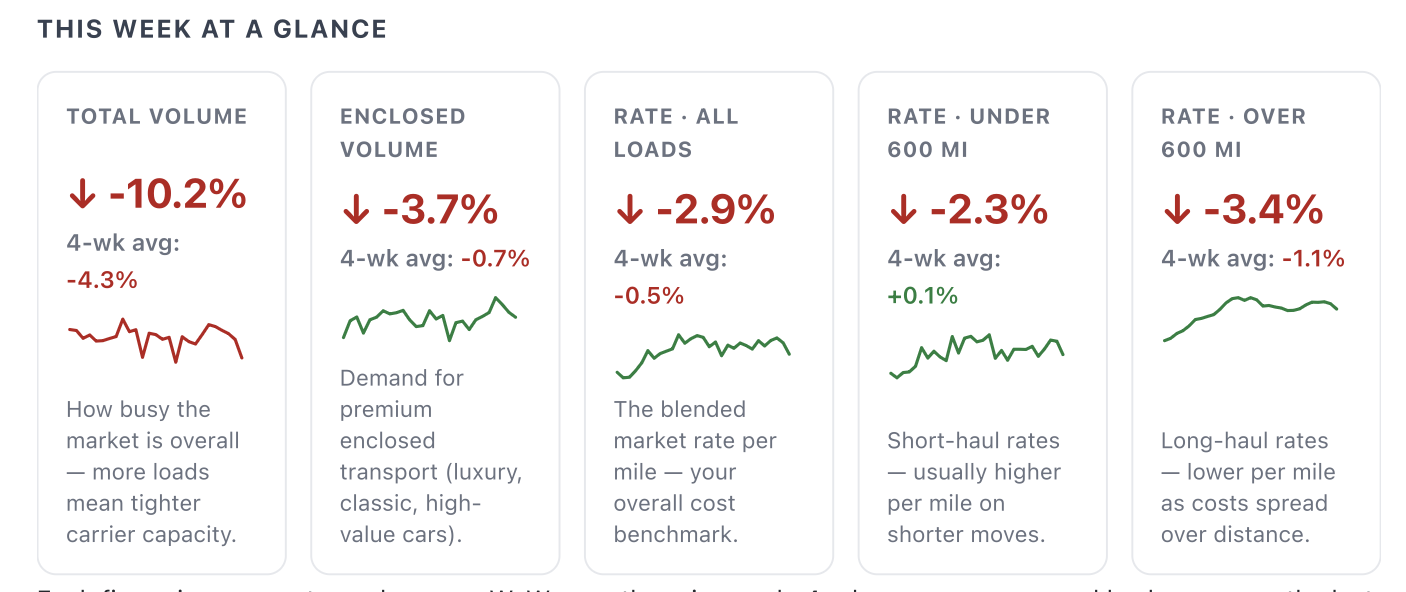
- Auto transport demand fell sharply for a fifth straight week (-10.2% after -3.2%), by far the steepest print in over two months – but the calendar explains much of it: a national holiday fell inside this reporting week, and the two comparable holiday weeks earlier in our series both fully reversed within a week. Rates eased for a second straight week across every segment we track – a genuine two-week pattern rather than the single soft print flagged previously, and worth watching for confirmation.
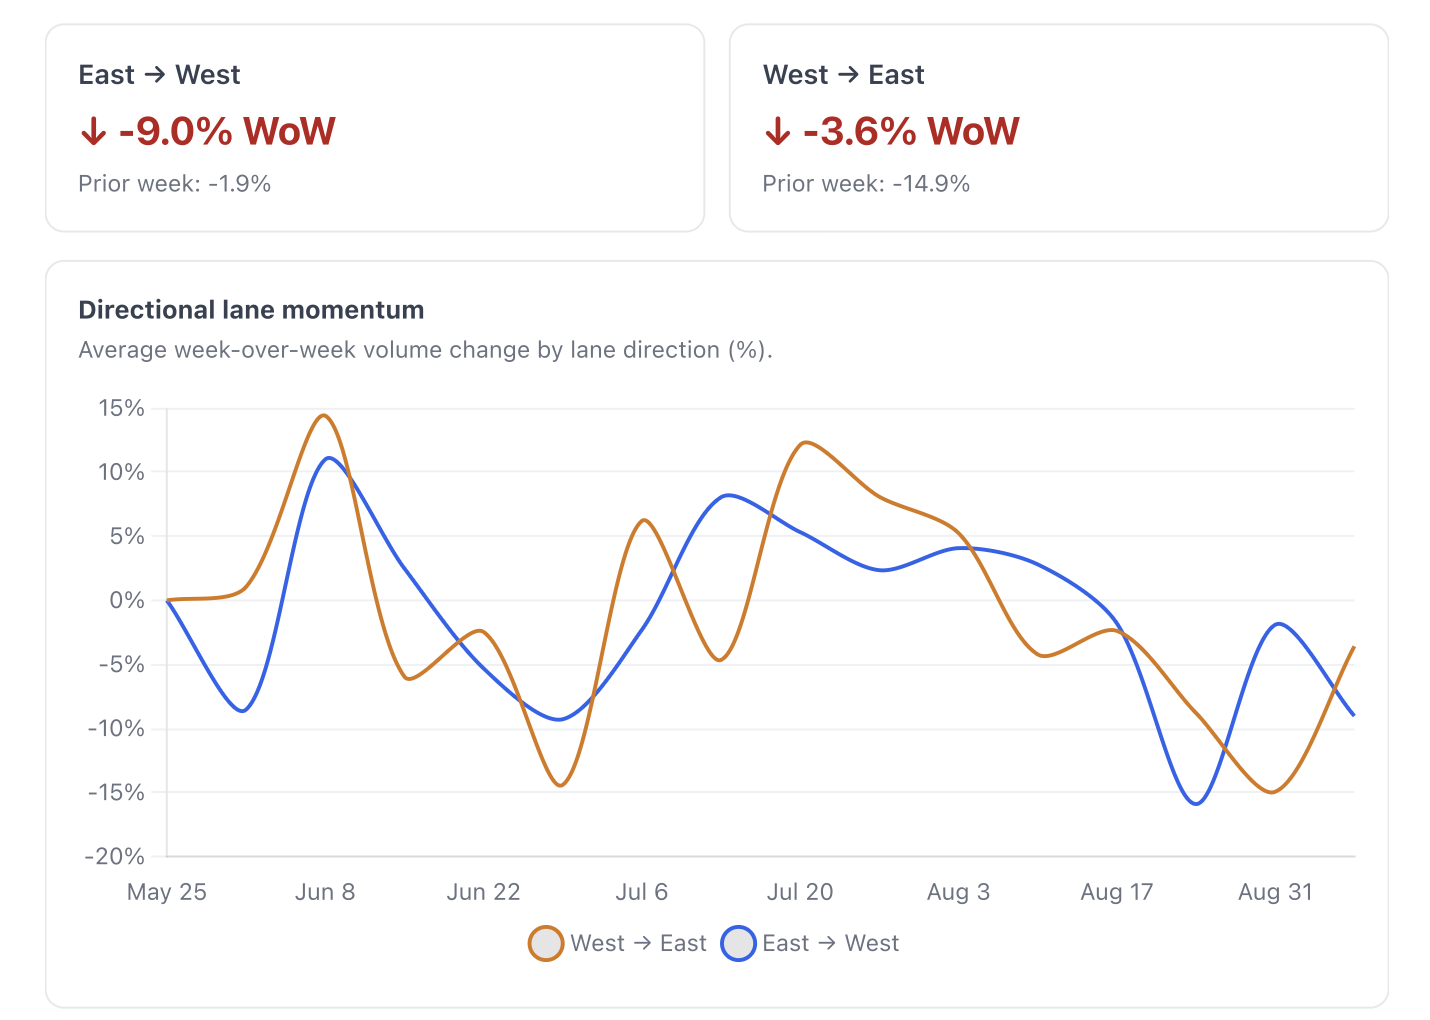
- Regional breadth narrowed to just one advancing market: the Northwest was the only region up on both volume and rate, nearly reversing its own sharp pullback from the prior week; every other region fell double digits or close to it. The cross-country lanes traded places again – the direction that held steady last week fell hard this week, and vice versa – continuing a pattern of alternating weekly pressure rather than a settled trend.
Volume trend
Pricing trend
Price segment detail
| Segment | WoW | 4-week average |
|---|---|---|
| All loads | ↓ -2.9% | ↓ -0.5% |
| Short-haul · under 600 mi | ↓ -2.3% | ↑ +0.1% |
| Long-haul · over 600 mi | ↓ -3.4% | ↓ -1.1% |
| Enclosed (premium) (volatile) | ↓ -1.3% | ↓ -0.2% |
Short-haul rates typically run higher per mile (fixed pickup/delivery effort over fewer miles); long-haul runs lower per mile.
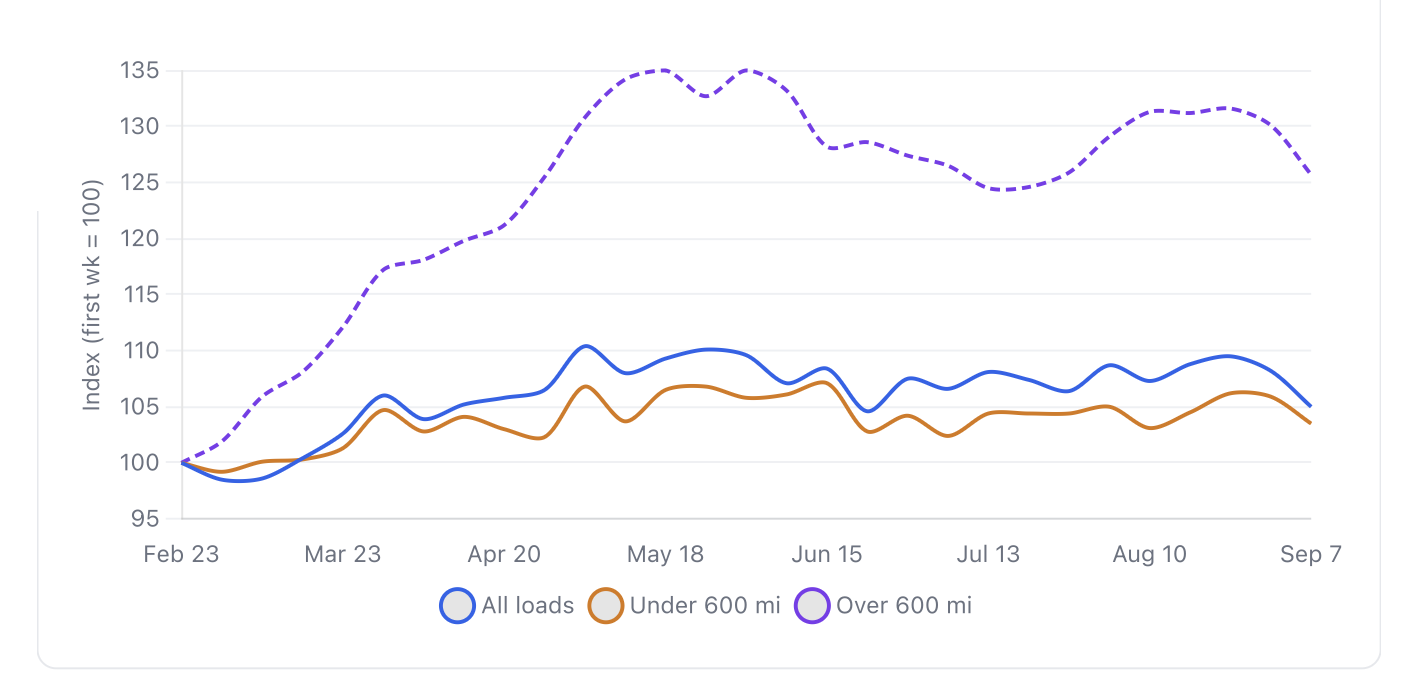
Enclosed (premium) is a small-sample segment, so single weeks can swing for reasons that have nothing to do with the wider market – read it on a multi-week basis rather than week to week. It is excluded from the rate index chart above so that sample noise does not distort the rebased lines.
Lane deep dive
Region deep-dive – volume & rate
Regions: NE – Northeast; SE – Southeast; SW – Southwest; MW – Midwest; NW – Northwest; South – South/South-Central
| Region | Volume WoW | Rate/MI WoW | Volume Trend |
|---|---|---|---|
| MW | ↓ -12.3% | ↓ -2.6% | Weakening |
| SE | ↓ -11.9% | ↓ -2.3% | Weakening |
| SW | ↓ -10.3% | ↓ -2.9% | Weakening |
| NE | ↓ -6.3% | ↓ -3.3% | Weakening |
| South | ↓ -3.2% | ↓ -1.3% | Weakening |
| NW | ↑ +1.1% | ↑ +3.6% | Improving |
Volume and rate/mile WoW by region. | Breadth narrowed to just one advancing market: the Northwest rose on both volume and rate – nearly reversing its own sharp pullback from the prior week, and the only region to post a positive rate print – while every other region eased double digits or close to it. The Midwest posted the widest single-week swing of the six, moving from a solid prior-week gain to this week’s steepest decline. The trend column compares this week’s volume change with last week’s.
What the data is telling us
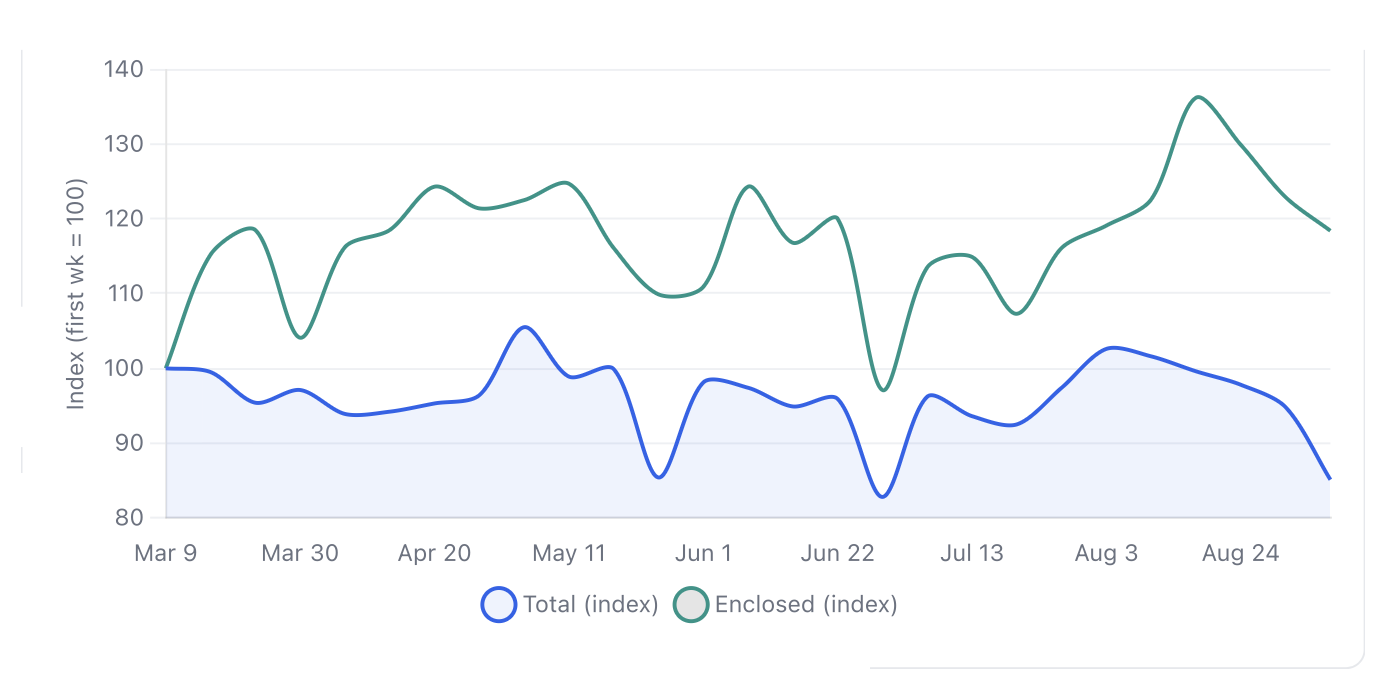
- Auto transport demand fell for a fifth consecutive week (-10.2%, after -3.2%, -1.8% and -2.0%), by far the widest single-week decline in over two months. A national holiday fell inside this reporting week, and the two comparable holiday weeks earlier in our series each fully reversed within a week – so treat this print as a calendar effect first and a demand signal second.
- Rates eased across every segment for a second straight week. The blended rate moved -2.9% (-0.5% on four weeks), short-haul eased -2.3%, and long-haul eased -3.4%. Unlike the rate decline we flagged in last week’s report, two consecutive weeks of broad-based easing is a more credible early signal that pricing power is shifting, not just noise.
- Regional breadth narrowed to just one advancing market. The Northwest rose +1.1% on volume – nearly reversing its own sharp pullback the prior week – with its rate up +3.6%, the only positive rate print of the six. Every other region fell double digits or close to it: Midwest -12.3%, Southeast -11.9%, South -10.8% and Southwest -10.3%.
- The cross-country lanes swapped roles again. East→West fell -9.0% after holding nearly flat the prior week (-1.9%), while West→East eased to -3.6% after a sharp prior-week decline (-14.9%). Two straight weeks of one direction absorbing the pressure while the other recovers points to carriers repositioning rather than a broad long-haul pullback.
- Premium enclosed volume held up meaningfully better than the broader market, down just -3.7% against the headline’s -10.2% – a third straight decline, but a far gentler one. Its four-week average (-0.7%) remains close to flat, and its rate barely moved (-1.3%).
- The Midwest posted the widest single-week reversal of the six regions, swinging from -6.9% the prior week to -12.3% this week with its rate down -2.6% – a reminder that any one week’s regional leader can flip fast in this market.
What to watch: A national holiday landed inside this reporting week, and holiday weeks in this series routinely print sharp single-week declines that fully reverse the following week – so treat next week’s headline as a calendar rebound rather than a trend confirmation. The more important thread is pricing: this is now two consecutive weeks of rates easing across every segment, a different pattern from the single soft print flagged previously, and worth confirming with a third week before reading it as a genuine shift. Beyond that, watch whether the Northwest’s rebound holds or reverses again, and whether the cross-country lanes settle into one consistent direction instead of trading places weekly. For standard open-carrier moves, normal lead times and stable budgeting still apply; for enclosed and high-value vehicles, book earlier.
– Daniel Mihaylov, Product Manager, Carrier Products
Methodology: Ship.Cars Market Read reflects marketplace activity for the last complete Monday–Sunday week (September 6 – 13, 2026). Every figure is a week-over-week or 4-week percentage change — absolute volumes and rates are not disclosed. Rate movements are calculated using a distance-adjusted methodology that compares loads within distance bands and limits the influence of extreme per-mile values. Figures are directional indicators, not a forecast, and may be revised as late loads post. Refreshed weekly. For informational purposes only.