This monthly market read looks at public economic and transportation signals through the lens of auto logistics, translating them into practical context for pricing, capacity, and planning.
Key takeaways
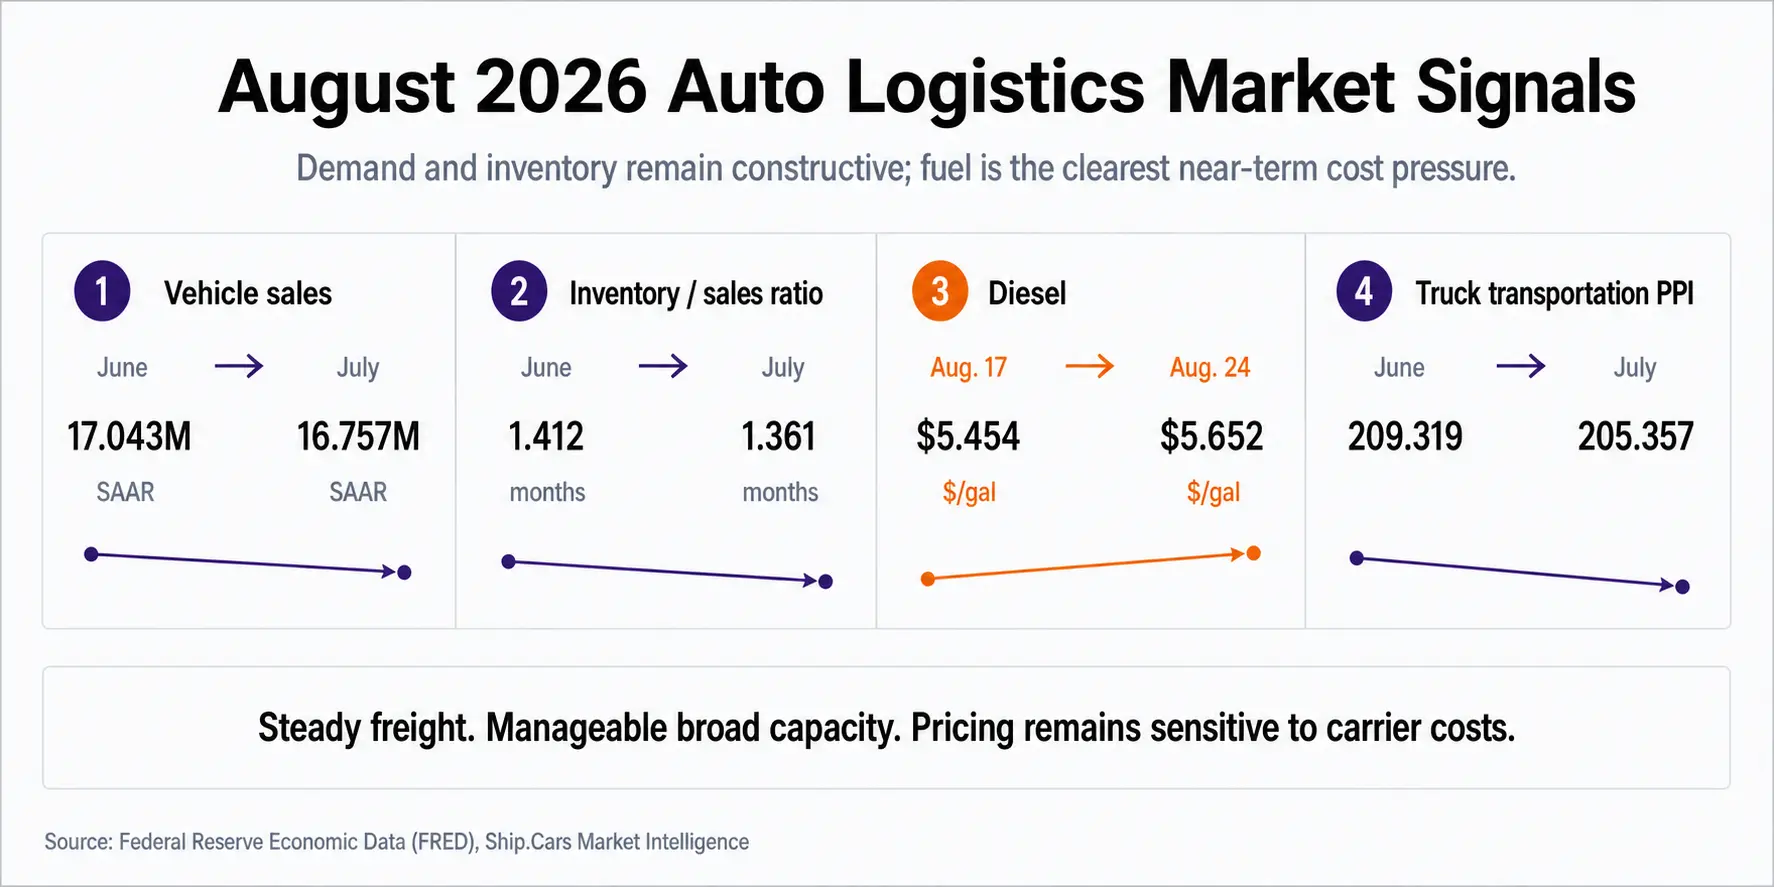
- Auto transport costs are being shaped more by carrier economics than by a surge in demand. Total vehicle sales eased from a 17.0 million SAAR pace in June to 16.8 million in July – enough to support regular transport work, but not enough to create a broad rush for trucks.
- Dealer inventory tightened relative to sales. That favors normal restocking and selective vehicle moves rather than a wave of freight caused by excess inventory.
- Fuel is still the signal doing the most damage to carrier economics. Diesel climbed from $5.454 per gallon on August 17 to $5.652 on August 24, confirming the fuel risk we were watching last month.
- The rest of the trucking market is sending a softer pricing signal. Truck transportation prices declined in July, which may limit how much pricing power carriers have. High diesel, however, makes it difficult for transport rates to fall too far.
- For September, the better planning assumption is steady freight with uneven lane economics. Fuel exposure, return-load opportunities, equipment needs, and where the truck ends up may matter more than small changes in national vehicle demand.
In this article
September Market Read: steady freight, expensive fuel
September begins with a familiar demand picture but a more complicated cost story.
Vehicle sales remain healthy enough to keep cars moving through the supply chain, while dealer inventory does not show signs of a major buildup. Nothing in the latest data points to a sudden freight boom – but there is not much evidence of a major slowdown either.
The tension is on the carrier side. Diesel continued climbing through late August, while broader truck transportation prices moved lower in July. In other words, the market is not necessarily giving carriers more pricing power, but one of their biggest day-to-day expenses is getting harder to absorb.
That creates an awkward middle ground for auto transport pricing. Shippers and brokers may not see enough demand pressure to justify significantly higher rates across the board. Carriers, meanwhile, still have to make the trip work at $5.65 diesel. The result is likely to be a market where the lane itself matters more than the national average.
A well-balanced route between active markets can behave very differently from a long-haul move that leaves a truck searching for its next load.
That is the September story to watch.
Vehicle demand is holding, while inventory gets a little tighter
Total U.S. vehicle sales eased from a 17.043 million seasonally adjusted annual rate, in June to 16.757 million in July. The decline is worth noting, but the level itself remains solid. Vehicle sales are still running at a pace that should keep dealer restocking, broker activity, and vehicle transportation demand moving.
What the number doesn’t give us is a reason to expect a nationwide scramble for truck capacity. A move from 17.0 million to 16.8 million is much closer to normalization than a demand shock.
Inventory adds another piece to that picture.
Domestic auto inventories declined from 212,991 units in June to 207,457 in July, while the inventory-to-sales ratio fell from 1.412 months to 1.361 months. Put simply, vehicle supply tightened relative to the pace at which vehicles were selling.
That is quite different from dealers sitting on rapidly growing inventories and needing to clear vehicles aggressively. The more likely transport pattern is the ordinary work of keeping inventory in the right places: restocking lots, moving vehicles between locations, and repositioning units where demand is stronger. That also lines up with the latest Ship.Cars Weekly Pulse data, where shorter-distance auto transport demand strengthened while long-haul demand remained stable to slightly softer.
Domestic auto retail sales offer a small additional positive signal. Sales increased from 150,871 units in June to 152,451 in July. That could give some support to shorter domestic plant-to-dealer flows, but the increase is too small to reshape the broader market on its own.
For dispatchers and carriers, that is an important distinction. A slightly better national sales number does not suddenly make every lane attractive. OEM activity, region, equipment type, truck position, and the likelihood of finding another load after delivery still have far more influence over whether an individual trip makes sense.
Overall, the demand side looks healthy without looking urgent. There should be freight to move. There just isn’t much evidence yet that significantly more freight will be chasing the same trucks.
How are diesel prices affecting auto transport costs?
This is where September gets more interesting.
The U.S. diesel sales price climbed from $5.454 per gallon on August 17 to $5.652 on August 24. Last month’s Market Intelligence identified fuel as the biggest cost risk to watch. Instead of easing, that pressure increased.
For car haulers, an extra twenty cents per gallon is not an abstract economic indicator. It goes into the truck every time it fuels.
The effect becomes more noticeable as the trip gets longer – and especially when the paid miles tell only part of the story. A carrier may have to drive empty to the pickup, travel additional miles because of the route, and then deadhead again after delivery before finding another vehicle. Higher diesel makes every one of those unpaid miles more expensive.
That does not mean every September quote should suddenly be higher. A well-balanced regional lane with plenty of follow-up freight may still attract strong carrier competition.
The harder moves are where fuel can become the deciding factor: long-haul routes, markets with poor return-load options, unusual equipment requirements, and pickups or deliveries that put the truck far from its next opportunity. On those loads, a quote that worked several weeks ago may simply not work anymore.
For brokers and shippers, that can show up as re-quotes, rejected offers, or a carrier accepting another load that leaves the truck in a better position. What looks like a pricing problem may actually be a trip-economics problem.
Why aren’t trucking prices rising with diesel?
This is the more interesting contradiction in this month’s data.
While diesel moved sharply higher, the Producer Price Index for truck transportation declined from 209.319 in June to 205.357 in July. The index has moved away from its recent highs, suggesting that the broader trucking market is not experiencing the kind of pricing pressure we would expect from a major freight or capacity squeeze.

So carriers are being squeezed from two directions.
The broader freight environment may limit how aggressively they can push rates higher, while diesel increases what it costs them to actually move the truck.
For auto logistics, that helps explain why the September pricing picture is unlikely to be as simple as “fuel went up, therefore rates go up.” The market still has to support the rate.
On common, well-balanced lanes – with good truck availability – competition may keep quotes relatively contained. On a difficult lane, the same fuel environment can make the gap between what a shipper wants to pay and what a carrier is willing to accept noticeably wider.
That is also why national averages only tell part of the story. Two loads with similar mileage can have very different economics once empty miles, route balance, equipment needs, pickup location, and the next available load enter the equation. Our recent analysis of directional auto transport rates and backhaul risk shows just how differently a trip can work depending on the market a truck is entering and leaving.
For carriers, September may therefore reward selectivity more than aggressive pricing. The question is not simply “Can I get a higher rate?” It is “Does this rate still make sense once I account for the whole trip?”
What this means for auto logistics
The September market does not currently call for dramatic changes in planning. It does call for closer attention to the details that determine whether an individual move works.
For pricing teams, recent fuel data matters. Quotes based on an older fuel environment can age quickly when diesel is moving by twenty cents per gallon in a week. Longer routes and moves with extra empty mileage deserve another look before assuming an older price still works.
For brokers and dispatchers, the cheapest available rate may not be the easiest rate to cover. A load that puts a carrier in a weak destination market can require more money even if the loaded mileage looks reasonable. Truck position before pickup and after delivery matters.
For carriers, the full trip matters more than the loaded leg. Revenue per loaded mile can look attractive while revenue per total mile tells a different story once deadhead and the next move are included. With diesel above $5.60 per gallon in the latest data, those unpaid miles become harder to ignore.
For shippers, dealers, and OEMs, current demand signals support regular transportation activity rather than a rush for capacity. Common lanes should remain relatively workable. More complicated moves may benefit from earlier planning or wider pickup windows rather than simply waiting for cheaper capacity.
For equipment and capacity planning, there is little in the current demand data that argues for aggressive expansion based on volume alone. Vehicle sales are healthy, but they are not accelerating sharply. September looks more like a month for making existing capacity work efficiently than preparing for a nationwide freight surge.
The common thread is simple: the national market looks relatively stable, but the economics of individual trips are getting less forgiving.
What to watch next month
Last month’s fuel warning materialized. This month, the question is whether diesel keeps climbing – and whether the rest of the market eventually responds.
If diesel stays near current levels or moves higher again, the gap between carrier operating costs and broader trucking pricing will become increasingly important. Difficult auto transport lanes would likely feel that pressure first. A meaningful decline in fuel, on the other hand, could give carriers some breathing room and make pricing more flexible on competitive routes.
Vehicle sales are the other side of the equation. July’s decline from 17.0 million to 16.8 million SAAR is modest. If sales remain around the mid-16 million range, the steady-demand read holds. Another meaningful decline would make the demand picture softer; a return above 17 million would strengthen it.
Inventory deserves attention alongside sales rather than on its own. The current 1.361-month inventory-to-sales ratio does not show an oversupplied market. If inventories begin climbing while sales weaken, the story changes: more vehicles could initially need repositioning, but softer retail movement could become a concern further ahead.
The truck transportation PPI may ultimately be the signal that helps resolve the current contradiction. If trucking prices continue falling while diesel remains expensive, carriers could face a tighter margin environment without gaining much additional pricing leverage. If trucking prices turn higher as well, the case for broader cost-supported transport pricing becomes stronger.
For now, our September read is steady vehicle demand, tighter inventory, expensive fuel, and a market increasingly sensitive to the economics of each individual lane.
Methodology note: This market read is based on publicly available economic and transportation indicators from the Federal Reserve Economic Data (FRED) database, including Total Vehicle Sales, Domestic Auto Inventories, U.S. Diesel Sales Price, Auto Inventory/Sales Ratio, Motor Vehicle Retail Sales: Domestic Autos, and the Producer Price Index for Truck Transportation.
Ship.Cars interprets these public signals through the lens of auto logistics. The analysis is intended as directional context for pricing and planning, not as a guarantee of future market conditions.